Insights
What Is Real Estate Syndication? A Guide for Accredited Investors
Oliver Thornton · March 14, 2025
Real estate syndication is a group investment in a specific property. One party — the sponsor — finds the deal, arranges the financing, and executes a business plan. A group of investors supply most of the equity and hold passive stakes. Profits are divided on terms agreed in writing before anyone contributes a dollar.
That is the whole concept. Everything else is detail about who does what, how the money is split, and what can go wrong. This guide covers each, from the perspective of a sponsor who runs these projects rather than a summary of the general idea.
What is real estate syndication?
A syndication exists because good real estate deals are frequently too large for one person and too small or too specific for institutional capital. A single Los Angeles infill rebuild can require several million dollars of equity. Few individuals write that cheque alone; few institutions get out of bed for it.
Syndication resolves that. Capital is assembled from a group, the property is bought by an entity formed for that one deal — usually a limited liability company or limited partnership — and each investor owns a share of that entity rather than a piece of the building directly.
Two features distinguish it from other ways of investing in property. It is deal-specific: you are shown an identified property and a plan for it, not a pool of assets to be chosen later. And it is passive for investors: the sponsor operates, and the investors, by design and for legal reasons, do not.
How does real estate syndication work, step by step?
- Sourcing. The sponsor finds a property and underwrites it — what it costs, what the work will cost, what it should sell or rent for, and what happens if those assumptions are wrong.
- Structuring. An entity is formed for the deal. The operating agreement sets out who contributes what, how profits are divided, who decides what, and how disputes are handled.
- The raise. The sponsor presents the opportunity to eligible investors through offering documents — typically a private placement memorandum, the operating agreement, and a subscription agreement.
- Closing. Investor capital is combined with debt financing and the property is acquired.
- Execution. The sponsor carries out the plan: entitlement, construction, renovation, leasing, management. Investors receive periodic reporting.
- Exit. The property is sold or refinanced. Proceeds are distributed according to the waterfall in the operating agreement.
The timeline varies enormously by strategy. A renovation may run twelve to eighteen months. A ground-up development with an entitlement phase can run several years, and may distribute nothing at all until the exit.
Who is involved: sponsor, general partner, limited partner
Most syndications use a two-party structure.
The sponsor — also called the general partner or GP — sources the deal, signs on the debt, executes the plan, handles reporting and distributions, and typically invests their own capital alongside investors. They carry the operational obligations and, usually, personal liability on any loan guarantee.
The limited partners — the investors — contribute capital and hold passive stakes. Their liability is limited to what they invested, and that limitation is precisely why they cannot take an operating role. Passivity is a structural feature, not a preference. The division is set out in more detail in the general partner versus limited partner guide.
What is a real estate syndicator?
A real estate syndicator is the party that organises and runs the syndication — the sponsor. In practice the role covers finding and underwriting deals, raising capital under the applicable securities exemption, arranging debt, running the project, reporting to investors, and managing the exit.
It is worth separating this from two things it is often confused with. A syndicator is not a broker: they are a principal in the deal, not an agent earning a commission on someone else's transaction. And a syndicator is not necessarily a builder — some manage from a desk and hire everything out, while vertically integrated operators carry construction in-house. That difference matters, because it determines who is accountable when a project runs over.
How the money is divided
Most syndications share profits through a waterfall — a defined order in which cash is distributed.
A common shape: investors first receive a preferred return, a stated annual rate paid on their capital before the sponsor participates in profit. Then invested capital is returned. Only after both are satisfied does remaining profit split between investors and sponsor on an agreed ratio.
The point of the structure is sequencing, not the specific numbers. A preferred return is a priority in the queue, not a guarantee — if the project does not produce cash, there is nothing to pay it from, and unpaid preferred return typically accrues rather than disappearing. Any specific rate, split, or fee is set by the individual offering's documents and varies between sponsors and between deals.
Fees vary too, and they are worth reading carefully: acquisition fees, asset management fees, construction management fees and disposition fees all appear in different combinations. The question is not whether fees exist but whether the total leaves the sponsor genuinely motivated by the outcome rather than by the transaction. Structure outlasts projections.
Syndication compared to other property investments
| Syndication | REIT | Private fund | |
|---|---|---|---|
| What you are buying | One identified property | Shares in a diversified company | A manager and a strategy |
| Known at commitment | The specific asset and plan | The portfolio and its history | Often not the assets — a blind pool |
| Liquidity | None until sale or refinance | Daily, if listed | None until wind-down |
| Diversification | Concentrated by design | Broad | Across the fund's assets |
| Who can invest | Generally accredited | Anyone | Generally accredited |
None of these is better in the abstract. A syndication offers something a fund cannot — the ability to inspect the actual asset before committing — and gives up diversification to do it. We compare the routes in more depth in the guide to passive real estate investing.
Who can invest in a real estate syndication?
Most syndications are offered under exemptions in Regulation D that limit participation to accredited investors, with some offerings permitting a limited number of sophisticated non-accredited investors. Accreditation is defined by the SEC on income, net worth, or professional credentials — the current thresholds are set out in the accredited investor requirements guide.
Two exemptions do most of the work, and the difference shapes how you will encounter offerings at all:
- Rule 506(b) — the sponsor may not advertise the offering publicly, and investors self-certify their status. This is why many syndications reach people only through existing relationships.
- Rule 506(c) — the sponsor may market publicly, but must take reasonable steps to verify accreditation, typically through documentation from an accountant or attorney.
What can go wrong
An honest list, because the risks are structural rather than exotic:
- Execution. Construction runs over budget, entitlement takes longer than modelled, a lease-up is slower than assumed. Time is the most common way returns erode.
- Market. Values or rents move against the plan between acquisition and exit.
- Leverage. Debt amplifies outcomes in both directions, and a loan maturing in a bad market forces decisions nobody wants to make.
- Sponsor. The plan is only as good as the party executing it — which is why sponsor diligence deserves more of your attention than the projected return.
- Illiquidity. If your circumstances change, you generally cannot exit early.
Private real estate investments are speculative and can lose some or all of the capital committed. That is not boilerplate; it is the actual risk.
Is real estate syndication a good investment?
It suits an investor who wants exposure to a specific property, can commit capital for years without needing it back, and is willing to do the work of evaluating a sponsor. It is a poor fit for anyone who may need liquidity, wants broad diversification from a small amount of capital, or does not want to read a hundred-page offering document.
The single largest determinant of outcome is not the property or the market — it is the operator. Two sponsors can buy identical buildings on the same street and produce entirely different results. That is why the useful diligence questions are about track record across a full cycle, co-investment, underwriting discipline, and how a sponsor communicates when something goes wrong.
Working with Assemble Capital
Assemble Capital is a Los Angeles residential development and syndication firm. We source and underwrite the deals, carry construction and development in-house rather than brokering them out, and syndicate each project with investors who hold passive stakes. The principals invest their own capital in every deal. You can read the four strategies we run or what we have completed.
If you are an accredited investor and want to understand how we structure and underwrite these projects, get in touch. Assemble Capital offerings are made only to accredited and otherwise eligible investors, and only through definitive offering documents — nothing on this page is an offer, a solicitation, or a recommendation to invest.
Frequently asked questions
What is real estate syndication?
Real estate syndication is a group investment in a specific property. A sponsor sources the deal, arranges financing and executes the business plan, while a group of investors contribute most of the equity and hold passive stakes. Profits are divided according to terms agreed in writing before the investment is made.
How does real estate syndication work?
The sponsor identifies and underwrites a property, forms an entity for the deal, raises equity from eligible investors through offering documents, combines it with debt to acquire the property, executes the business plan, and distributes proceeds when the property is sold or refinanced.
What is a real estate syndicator?
The syndicator is the sponsor — the party that organises and runs the syndication. The role covers sourcing and underwriting deals, raising capital under the applicable securities exemption, arranging debt, executing the project, reporting to investors, and managing the exit. A syndicator is a principal in the deal, not a broker earning commission on someone else's transaction.
Who can invest in a real estate syndication?
Most syndications rely on exemptions that limit participation to accredited investors, though some permit a limited number of sophisticated non-accredited investors. Accreditation is defined by the SEC on income, net worth, or professional credentials.
What is the difference between a syndication and a REIT?
A syndication is a private investment in one identified property, with capital committed until that property is sold or refinanced. A REIT is a company holding a diversified portfolio, usually publicly traded and sellable on any market day. Syndications offer a specific, inspectable asset; REITs offer liquidity and diversification.
How long does a real estate syndication last?
It depends entirely on the strategy. A renovation may run twelve to eighteen months; a ground-up development with an entitlement phase can run several years. Development projects may distribute nothing before exit. The expected hold is set out in each offering's documents, and business plans can and do run longer than modelled.
Is real estate syndication a good investment?
That depends on the specific deal, the sponsor, and whether the investor can commit capital for years without needing access to it. Private real estate is speculative, illiquid, and can lose some or all of the capital invested. The sponsor's track record and the structure of the deal matter more to the outcome than the projected return.
Sources and review
Accredited investor standards and the offering mechanics of Rule 506(b) and Rule 506(c) are set by the U.S. Securities and Exchange Commission under Regulation D and are subject to change. Structures, fees, hold periods and waterfall terms described here are general market practice and vary by individual offering; the governing terms are always those in that offering's own documents.
This article is general educational information, not investment, legal or tax advice, and not an offer or solicitation of any investment. Consult your own financial, legal and tax advisors before making any investment decision.
This article is for general informational and educational purposes only. It is not, and should not be relied upon as, investment, legal, tax, or accounting advice, and it is not a recommendation or endorsement of any strategy or investment. Consult your own financial, tax, and legal advisors before making any investment decision. See our full Risk Disclosures for additional information.
Related Reading
Keep going.
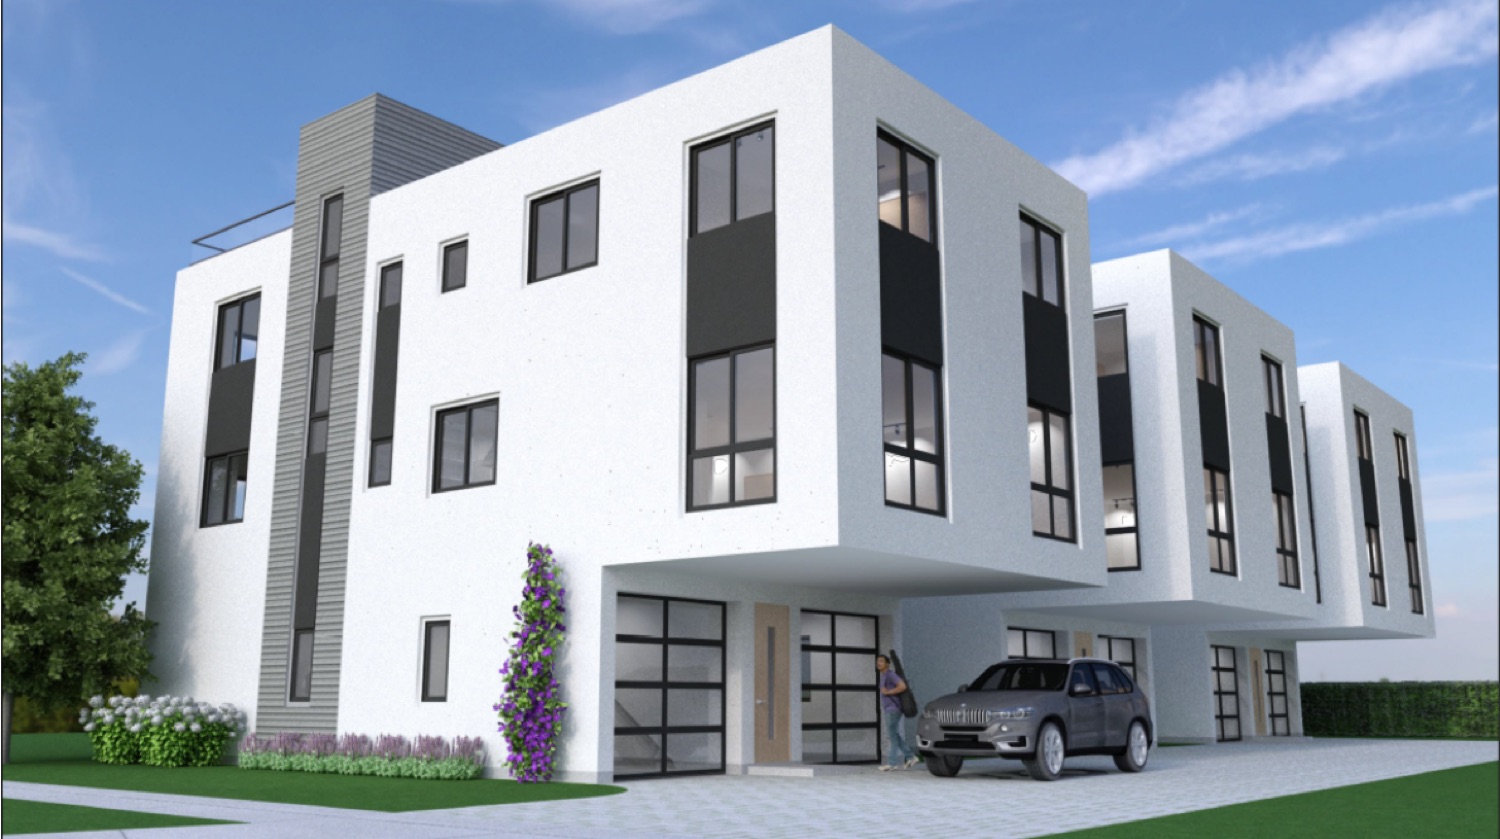
Or see how this plays out in practice: All four Assemble Capital strategies.
Future Opportunities
Want to invest in the next one?
Get in touch and we'll walk you through the model, the pipeline, and what a specific offering looks like.
Contacting us is not an offer, commitment, or investment. Any offering is made only through definitive offering documents to eligible investors.