Learning Center
How Prop 37 Helps First-Time Buyers Purchase New SB 684 and AB 1751 Homes
Oliver Thornton · November 6, 2026
General information only. This article is educational and is not legal, tax, financial, lending or investment advice. Do your own due diligence and confirm everything with your own qualified professionals before relying on it. Read the full disclaimer.
For most first-time buyers in Los Angeles, the monthly payment is not the first obstacle. The down payment is. A 20 percent down payment on a $1,000,000 home is $200,000, which can take a renter a decade or more to save.
Proposition 37, approved by California voters on November 3, 2026, targets exactly that problem, but only for newly built homes. That restriction is what connects it to the state’s new ownership laws, SB 684 and SB 1123 and AB 1751. Those laws make new fee-simple homes easier to build, and Prop 37 helps buyers afford them.
Prop 37 in Brief
- CalHFA can lend up to 17 percent of the purchase price as a fixed-rate second mortgage, funded by up to $25 billion in revenue bonds.
- The buyer puts in at least 3 percent of their own money. Together that makes a 20 percent down payment, which generally means no private mortgage insurance on the first loan.
- The home must be newly built, and the buyer must be its first purchaser.
- The buyer must have lived in California for a year, earn no more than 200 percent of area median income, and move in within 60 days of closing.
- The price cap is 125 percent of the county’s one-unit conforming loan limit, about $1.56 million in Los Angeles County based on the 2026 limit.
- CalHFA has up to one year after the measure takes effect to launch. No loans are available yet.
Prop 37 was designed with first-time buyers and renters in mind, but the measure does not require borrowers to be first-time buyers. Anyone who meets the income, residency and occupancy rules can apply.
Why SB 684 and SB 1123 Homes Fit
An SB 684 project replaces one older house or small rental building with up to ten new homes, each on its own fee-simple lot. SB 1123 extends the same approach to qualifying vacant single-family lots. Those homes line up with Prop 37 in four ways:
- They are new construction. Every home in an SB 684 project is sold for the first time, so every first buyer meets Prop 37’s first-purchaser rule.
- They are the right product type. Prop 37 covers stand-alone homes, townhomes, row houses and condominiums. A fee-simple small-lot home fits that definition.
- They are sized to stay under the cap. SB 684 limits the average home to 1,750 net habitable square feet. Smaller homes on smaller lots tend to cost less than a typical detached house in the same neighborhood, so more of them can fall under the Prop 37 price cap.
- They finance like houses. Each home has its own parcel number, so lenders can underwrite it as a single-family home. That should make it simpler to pair a conventional first mortgage with a Prop 37 second mortgage. See how SB 684 homes are financed.
Why AB 1751 Townhomes Fit
AB 1751, the Missing Middle Townhome Ownership Act, takes effect January 1, 2027. It allows ministerial approval of for-sale townhome projects of up to 150 homes. Its homes are three stories or less, average no more than 1,750 net habitable square feet, and can each sit on a fee-simple lot of at least 600 square feet.
Townhomes and row houses are named in Prop 37’s definition of an eligible home. Because AB 1751 projects are new construction, every first buyer of an AB 1751 townhome priced under the cap could be eligible.
The timing also lines up. AB 1751 projects can begin entitlement in 2027, and CalHFA has until roughly the end of 2027 to launch Prop 37. The first homes built under AB 1751 should reach the market after Prop 37 loans are available.
On AB 1751 projects of 11 or more homes, 10 percent of the homes must be sold at an affordable housing cost to lower-income households. Those homes have their own rules and buyer programs. Prop 37 matters most for the market-rate homes in those projects, which are aimed at the middle-income buyers Prop 37 is written for.
What a Buyer Should Check
- The price against the cap. On the Westside, some new homes will be priced above the Prop 37 limit. The cap is reset each year when the FHFA publishes new conforming loan limits.
- Income against the limit. The 200 percent ceiling is measured by family size for the county or metro area where the home is located.
- The 3 percent. It must come from the buyer’s own funds, not a grant or borrowed money.
- Both payments. The Prop 37 loan is repaid monthly alongside the first mortgage, and the buyer must qualify for the combined payment.
- Timing. The program has to be running and funded when the buyer closes, and the $25 billion will not stretch to every buyer.
- Representation. Prop 37 requires buyers to work with a licensed California real estate agent or broker of their choice.
- Recorded parcels. For fee-simple homes, confirm that the final map has recorded and the home has its own parcel number before closing.
How It Fits Our Model
Assemble Capital builds fee-simple, for-sale homes on Los Angeles infill lots and sells them one at a time to owner-occupants. Our current Culver City projects are SB 684 projects, and as AB 1751 takes effect, part of our syndication model will be facilitating AB 1751 townhome projects where a site qualifies.
Prop 37 is aimed at the buyers those homes are built for: households who can carry a mortgage payment but have not been able to save a full down payment. As CalHFA publishes its program rules, we plan to:
- Track the annual price cap and income limits for the counties where we build.
- Review the optional qualified builder option and its labor and construction-defect terms, project by project.
- Make sure buyers of our homes, and their agents and lenders, know whether a home is eligible.
Prop 37 is new, and until CalHFA launches it, nobody knows the interest rate, how quickly the bonds will sell, or how many buyers it will reach. We will share what we learn as the program takes shape.
Frequently Asked Questions
Can I use Prop 37 to buy an SB 684 home?
Generally yes, if you are the first purchaser of the newly built home, its price is under the county cap, and you meet the income, residency and occupancy rules. Fee-simple SB 684 and SB 1123 homes fit the measure’s definition of a single-family home.
Will AB 1751 townhomes qualify for Prop 37?
Townhomes and row houses are listed in Prop 37’s definition of an eligible home, so a newly built AB 1751 townhome sold to its first owner can qualify, subject to the price cap. AB 1751 takes effect January 1, 2027.
Do I have to be a first-time buyer to use Prop 37?
No. Prop 37 is aimed at first-time buyers and renters, but the measure does not require it. You must have lived in California for a year, earn no more than 200% of area median income and live in the home.
What is the Prop 37 price limit in Los Angeles County?
125% of the county’s one-unit conforming loan limit. Based on the 2026 limit, that is about $1.56 million in Los Angeles County, and it changes every year.
Can I use Prop 37 to buy a resale SB 684 home?
No. Prop 37 requires the borrower to be the first purchaser of the home, so it only applies to the first sale of a newly built home.
Sources and Review
Prop 37 provisions summarized from the official voter guide and the measure text filed with the Attorney General. SB 684, SB 1123 and AB 1751 details are covered in our SB 684 guide and AB 1751 article. General information, not lending or legal advice. Eligibility, rates and terms will be set by CalHFA; buyers should confirm them with CalHFA or a participating lender.
Important Disclaimer
This article is published by Assemble Capital for general informational and educational purposes only. It is not legal, tax, accounting, lending, appraisal, real estate brokerage or investment advice, and it is not an offer to sell or a solicitation of an offer to buy any security. Laws, regulations, government programs, lending practices, market conditions and local procedures change often and vary by jurisdiction and by property. The information here may be incomplete, out of date or not applicable to your situation, and we have no obligation to update it.
No one, including investors, lenders, property owners, buyers, sellers, agents, brokers, wholesalers or developers, should rely on this article in making any decision. Before acting on any topic discussed here, independently verify the information and conduct your own due diligence with qualified legal, tax, financial, lending, appraisal and real estate professionals and the applicable government agencies.
References to projects, timelines, approvals, appraisals, financing, prices or market conditions are illustrative, may change, and are not predictions, promises or guarantees of any result. Past performance is not indicative of future results.
Reading this article or contacting us does not create an attorney-client, advisory, fiduciary, agency, brokerage or other relationship with Assemble Capital, its affiliates or its principals. Assemble Capital makes no representation or warranty, express or implied, as to the accuracy, completeness or timeliness of this content and, to the fullest extent permitted by law, disclaims all liability for any loss or damage arising from any reliance on it. Use of this site is subject to our Terms of Service and Risks & Disclosures.
Related Reading
Keep Going.
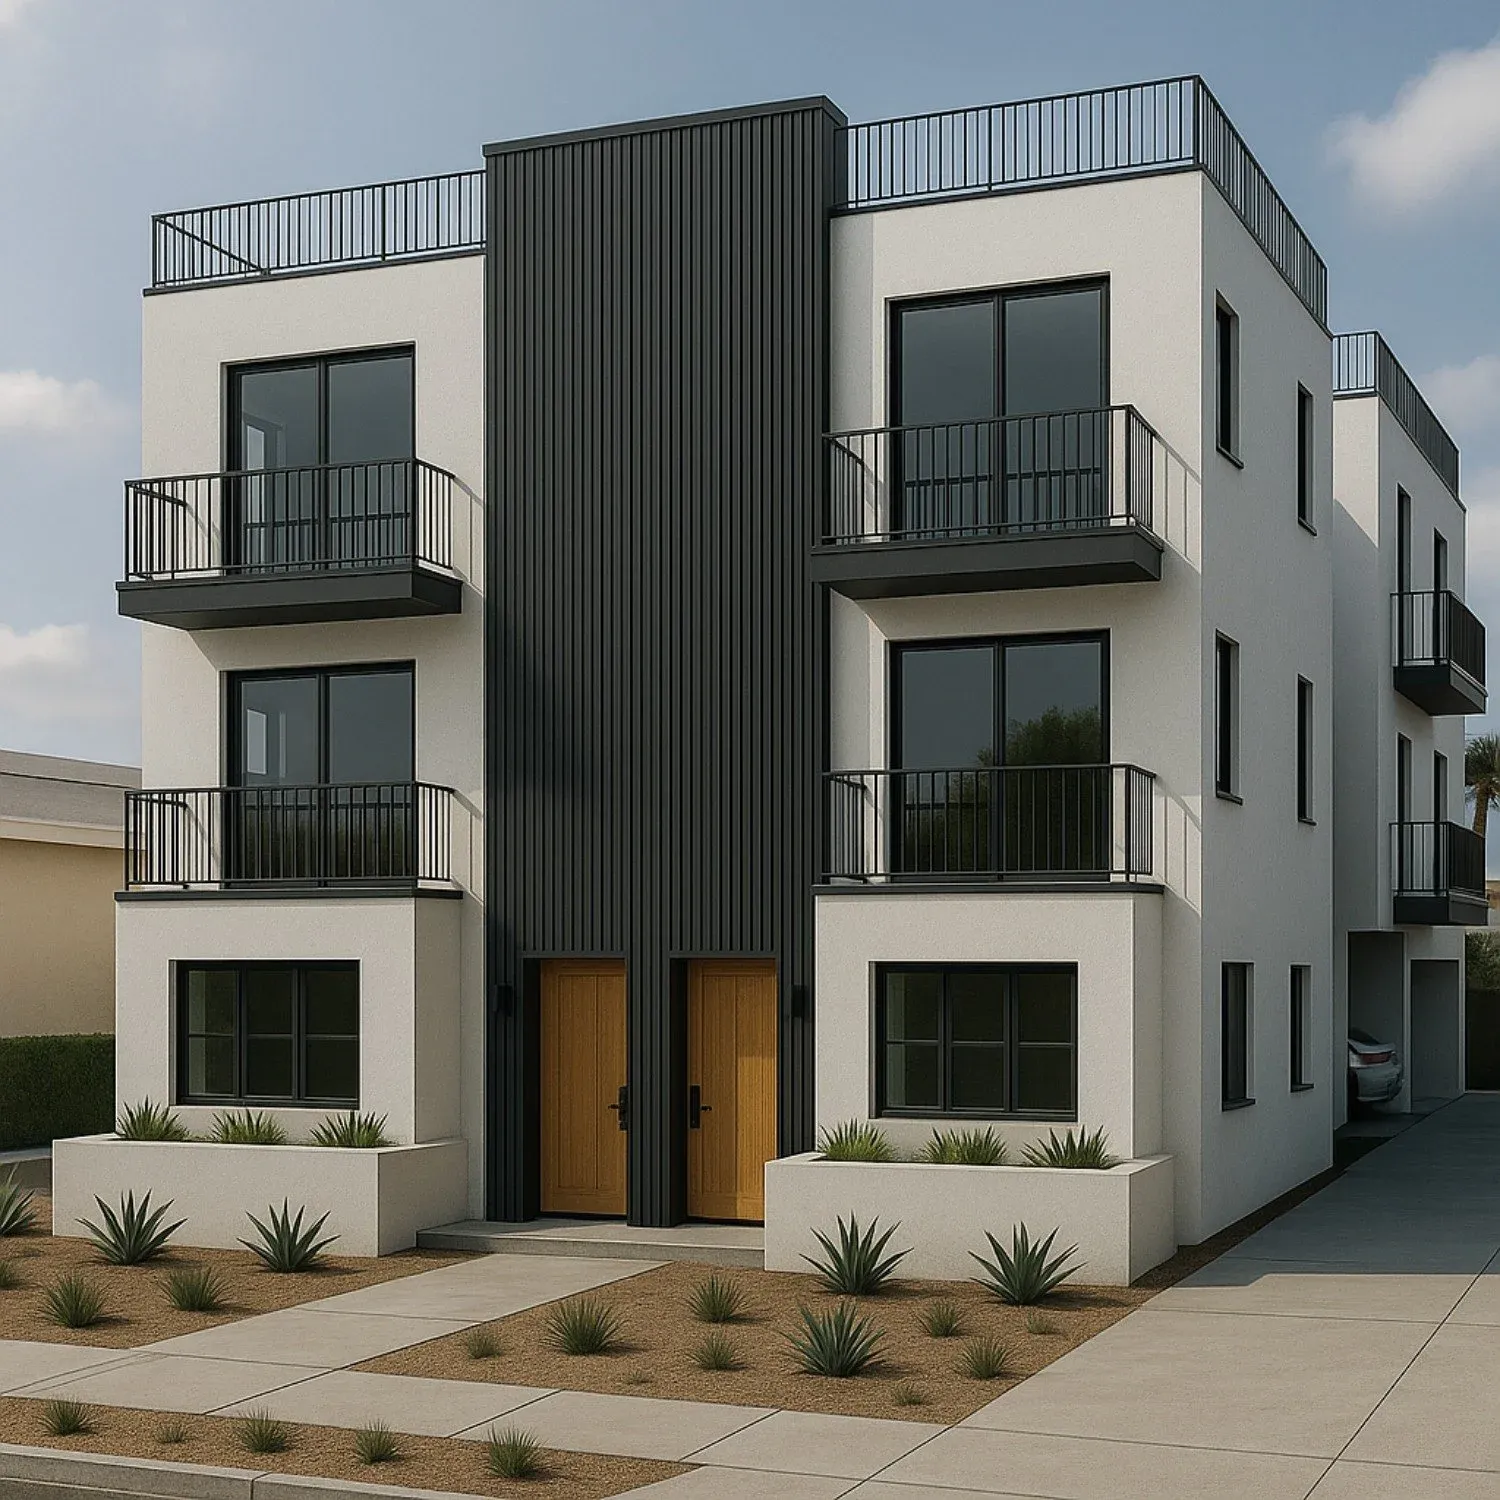
Or see how this plays out in practice: SB 684/1123 Fee Simple Subdivisions.
Work With Us
Investing, or Have a Property?
Contacting us is not an offer, commitment or investment. Any offering is made only through definitive offering documents to eligible investors with whom we have a pre-existing relationship.