Insights
Can Buyers Get a Conventional Mortgage on an SB 684 Home?
Oliver Thornton · October 24, 2026
General information only. This article is educational and is not legal, tax, financial, lending or investment advice. Do your own due diligence and confirm everything with your own qualified professionals before relying on it. Read the full disclaimer.
The most important feature of a fee-simple SB 684 home may be one buyers never see: it can be financed like an ordinary house. That single fact shapes who can buy these homes, how fast they sell, and what they sell for.
Why Fee Simple Finances Like a House
Each SB 684 home sits on its own legal lot, with its own assessor’s parcel number, owned outright by the buyer. To a lender, that looks like a single-family home: there is no shared building, no condominium project to review, and no fractional ownership. Buyers can generally use the same conventional mortgages, and often the same first-time-buyer programs, they would use for any other house.
How It Compares
| Fee-simple small-lot home | Condominium | Tenancy in common | |
|---|---|---|---|
| What you own | The home and the land under it | A unit plus a share of common areas | A fractional share of the whole property |
| Typical loan | Standard single-family mortgage | Condo mortgage, subject to project review | Specialized fractional TIC loan |
| Project-level review | Generally none | Often required | Lender-specific |
| Buyer pool | Broadest | Broad | Narrowest |
Why This Matters for Sellers and Investors
A deeper buyer pool supports pricing and shortens time on market, which in turn shortens the time a construction loan is outstanding. It is a big part of why fee-simple subdivision is generally a stronger exit than a condo or TIC on the same site, and why we choose it wherever a site qualifies. See also how fee-simple small-lot homes are priced.
What Buyers Should Still Check
- That the final map has recorded and the home has its own parcel number
- Any shared-driveway easements and maintenance agreement
- The appraisal, which will rely on comparable sales of similar new homes
- Program-specific property requirements if using FHA, VA or other programs
General information, not lending advice. Loan availability and terms depend on the borrower, the property and the lender.
Frequently Asked Questions
Can I use a conventional mortgage to buy an SB 684 home?
Usually yes. A fee-simple SB 684 home sits on its own legal lot with its own parcel number, so lenders generally underwrite it like any other single-family home.
Is financing different from buying a condo?
Condo loans can depend on the lender's review of the whole condominium project, including its budget and owner-occupancy. A fee-simple home generally doesn't require that project-level review.
Can first-time buyers use FHA or other programs on SB 684 homes?
Often, subject to the program's normal property and borrower requirements. Buyers should confirm eligibility with their lender.
Why does financing matter so much for small-lot homes?
The easier a home is to finance, the more buyers can purchase it, which supports both price and speed of sale.
Important Disclaimer
This article is published by Assemble Capital for general informational and educational purposes only. It is not legal, tax, accounting, lending, appraisal, real estate brokerage or investment advice, and it is not an offer to sell or a solicitation of an offer to buy any security. Laws, regulations, government programs, lending practices, market conditions and local procedures change often and vary by jurisdiction and by property. The information here may be incomplete, out of date or not applicable to your situation, and we have no obligation to update it.
No one, including investors, lenders, property owners, buyers, sellers, agents, brokers, wholesalers or developers, should rely on this article in making any decision. Before acting on any topic discussed here, independently verify the information and conduct your own due diligence with qualified legal, tax, financial, lending, appraisal and real estate professionals and the applicable government agencies.
References to projects, timelines, approvals, appraisals, financing, prices or market conditions are illustrative, may change, and are not predictions, promises or guarantees of any result. Past performance is not indicative of future results.
Reading this article or contacting us does not create an attorney-client, advisory, fiduciary, agency, brokerage or other relationship with Assemble Capital, its affiliates or its principals. Assemble Capital makes no representation or warranty, express or implied, as to the accuracy, completeness or timeliness of this content and, to the fullest extent permitted by law, disclaims all liability for any loss or damage arising from any reliance on it. Use of this site is subject to our Terms of Service and Risks & Disclosures.
Related Reading
Keep Going.
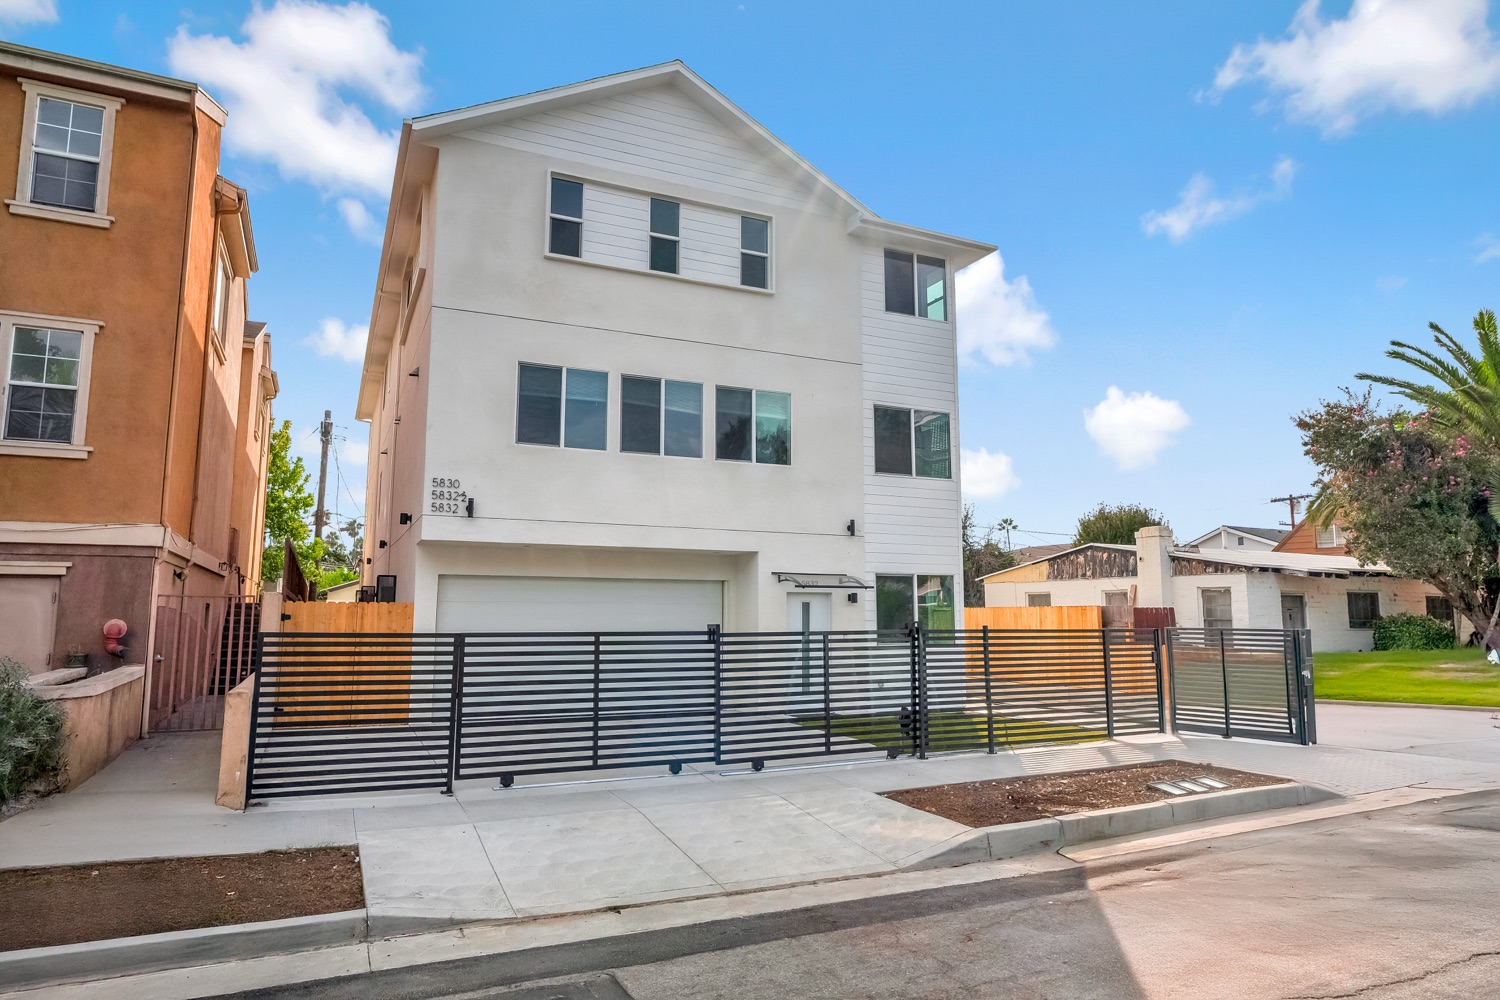
Or see how this plays out in practice: SB 684/1123 Fee Simple Subdivisions.
Work With Us
Investing, or Have a Property?
Contacting us is not an offer, commitment or investment. Any offering is made only through definitive offering documents to eligible investors with whom we have a pre-existing relationship.